- HOME
- Revenue Recognition
- Membership revenue recognition: Key challenges & solutions
Membership revenue recognition: Key challenges & solutions
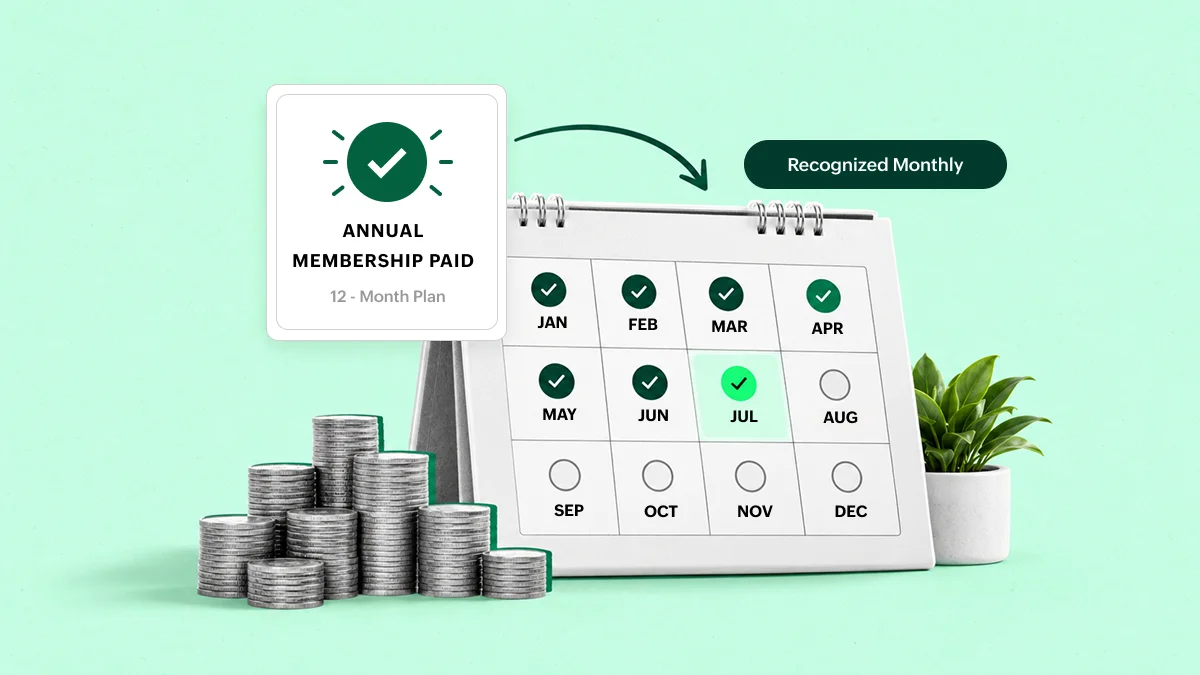
It is quite common to confuse memberships with subscriptions. In both, there is a recurring revenue for ongoing access. The only thing is that memberships come with a few quirks that easily go unnoticed: a one-time user registration fee that isn't actually earned when the membership starts, a member plan that packages facility access, special sessions, and discounts into a single price, or a lifetime membership that doesn't necessarily have a fixed end date—each of these introduces a revenue recognition nuance that doesn't come up with usual subscriptions.
Whether you own a gym, a library, a recreation club, or a membership-based community, the underlying standard is still the same five-step model of revenue recognition. What changes is how that model is applied to membership structures. This article goes through the common challenges in membership revenue recognition and how to combat them.
Joining and initiation fees
Membership businesses usually charge a one-time joining or registration fee outside the membership fee. As this fee is non-refundable, many businesses recognize it as soon as it is collected.
Solution: A non-refundable joining fee is not a distinct performance obligation on its own. It's the gateway to the actual membership the member is paying for and not a standalone transaction. As it doesn't transfer a separate good or service to the member, it should be recognized over the expected membership period rather than upfront. The expected period needs to be estimated reasonably based on historical member patterns.
Bundled membership tiers and perks
Membership packages often bundle multiple benefits into the package price. Facility access, exclusive sessions, guest passes, event invites, and the like are all distinct performance obligations if the member could benefit from them separately.
Solution: All the benefits need to be unbundled into separate line items, with the total membership price allocated across them, based on their standalone selling prices.
Benefits that aren't straightforward cash transactions
Membership benefits usually include things like member-only pricing, offers on renewals, discount coupons, and similar perks. These benefits don't have a market price on their own. As per IFRS 15, benefits like these should be considered a "material right" — a distinct performance obligation as the members get access to these because of the membership.
Solution: In revenue recognition accounting for material rights, a portion of the membership fee should be allocated and recognized when the benefit is used or lapses. It should not be recognized upfront. This is one of the common mistakes in membership revenue recognition as these benefits don't look like a separate product or service.
If the membership includes prepaid credits, bonus sessions, or promotional balances that are not used by the member, the same breakage principles that apply to gift cards apply here. Expected breakage can be recognized in proportion to redemption patterns. See our guide to gift card and breakage accounting for how that estimation works in detail.
Lifetime memberships
Revenue from a membership with one-year validity is straightforward to recognize. However, lifetime memberships have no end date and there is no clear period to spread the revenue across.
Solution: In such cases, the business needs to approximately identify the membership duration based on past trends and then recognize revenue over that period instead of recognizing the full amount upfront. This estimate should be revisited periodically as member patterns become clearer.
Renewals — new contract or continuation?
When a membership renews, the question of whether that renewal should be treated as a new contract or as an extension of the existing contract arises. This affects how remaining obligations like unallocated joining fees and material rights are treated.
Solution: Based on the original agreement, this needs to be applied consistently across all contracts. If auto-renewal was expected and priced into the agreement, it should be treated as a continuation of the existing contract.
Cancellations and non-refundable deposits
Cancellation terms in membership contracts are typically stricter than their subscription counterparts. Annual fees may be non-refundable beyond a certain point. This raises the question of how revenue should be recognized for the remaining period if a member cancels before the end of the term.
Solution: Non-refundable doesn't mean that revenue can be instantly recognized upon cancellation. It depends on how businesses handle cancellations. Some membership contracts allow access even after cancellation, while some cease all benefits as soon as the member cancels. The recognition treatment on cancellation should be applied consistently across all members who cancel under the same terms.
Group, family, and corporate memberships
In group and corporate memberships, the paying party is one, but the benefit is typically utilized by a larger group of members who can be added or removed mid-term.
Solution: Revenue recognition should follow the contract's terms, but the business should have a way to track how addition and removal of members affects the transaction price and remaining obligations. This should be handled similarly to how a plan upgrades and downgrades are treated, but applied at the level of individual seat count.
How Zoho Billing supports membership revenue recognition
Zoho Billing helps membership-based businesses automate revenue recognition and maintain accurate financial records as membership plans, billing cycles, and customer subscriptions change. It recognizes revenue over the contract period instead of treating it entirely upfront, helping businesses align revenue with what has been delivered to the member. It also supports handling changes such as plan upgrades, downgrades, cancellations, and refunds, helping businesses account for their impact on revenue schedules.
By automating these processes, Zoho Billing reduces manual calculations and the risk of errors while providing greater visibility into recognized and deferred revenue. This is particularly useful for businesses managing a large volume of memberships across different plans, billing frequencies, and pricing structures.
Conclusion
Membership revenue recognition often goes wrong because membership businesses treat it the same as a generic subscription, without accounting for differences like registration fees, material rights, lifetime memberships, and other factors. Treating each of these as separate obligations wherever necessary and applying the correct revenue recognition treatment is what keeps membership revenue accurate. A well-defined revenue recognition process, supported by automation and appropriate accounting practices, can reduce manual effort, minimize errors, and make it easier to manage growing membership volumes. By establishing consistent recognition policies and regularly reviewing revenue schedules, membership-based businesses can maintain compliance while gaining better visibility into their financial health and future revenue.
Frequently asked questions (FAQs)
Usually no. Joining fees don't represent a distinct obligation and should be recognized over the expected membership period rather than upfront, even if the fee is non-refundable.
As there is no contractual end date, the business needs to estimate the expected membership period based on past membership patterns and recognize revenue over that estimated period.
Material right is a benefit the membership grants that gives the member access to something that they wouldn't get without being a member. This may include benefits like wallet credits, discounted prices on renewals, member-only pricing, and the like. Under IFRS 15, this can be treated as its own performance obligation, with part of the transaction price allocated to it and recognized separately.
Not necessarily. If auto-renewal was anticipated and priced into the original contract, it's generally treated as a continuation of the existing arrangement rather than a brand-new contract.
It depends on whether the business retains an ongoing obligation to provide access. Non-refundable doesn't automatically mean the remaining revenue can be recognized immediately. The treatment should follow the business' stated cancellation policy, applied consistently to every member under the same terms.
Zoho Billing's manual revenue recognition feature, allows recognition to be controlled at the line-item level, which can accommodate non-standard schedules like joining fees and material rights. Zoho Billing has a built-in revenue recognition module that enables membership businesses to recognize revenue over the period of membership.